(855) 369-9993

About Attorney Nicole Duncan

Property Division Lawyer in Beverly Hills, California

Property division is where most Beverly Hills divorce outcomes are decided — characterizing and valuing the family home, closely held businesses, royalties, investment accounts, and retirement plans under California community property law. Duncan Family Law builds the tracing and valuation record before settlement talks begin. Nicole Duncan, Esq. handles every matter directly from consultation through final judgment.

Schedule a Consultation
Tell us briefly what you're facing. A member of our team will follow up regarding next steps.
Submitting this form does not create an attorney-client relationship.

The Attorney

Beverly Hills Property Division Attorney Nicole Duncan, Esq.

Duncan Family Law is a boutique family law firm founded and led by Nicole Duncan, Esq., a California family law attorney whose practice focuses on divorce, parentage, complex property division, and marital agreements throughout Los Angeles County. She regularly appears before the Los Angeles County Superior Court, including the Stanley Mosk Courthouse and other family law divisions, and advises clients based on how property division actually plays out in these courts, not how it is supposed to work in theory.

Nicole holds a Juris Doctor from Whittier Law School and a Bachelor of Business Administration from the USC Marshall School of Business, where she completed the Lloyd Greif Center for Entrepreneurial Studies. She also holds a Certificate in International Law from King’s College London, which is relevant when a couple holds property outside the United States.

In property division matters involving a family business, entertainment income, or a significant real estate portfolio, direct attorney involvement from start to finish is how a fair division is actually secured.

About Attorney Nicole Duncan

Attorney Credentials

Attorney Credentials

  • California State Bar No. 328341, Active, admitted 2019
  • D., Whittier Law School
  • B.A., USC Marshall School of Business — Lloyd Greif Center for Entrepreneurial Studies
  • Certificate in International Law, King’s College London
  • Licensed: California and Colorado
  • Member: State Bar of California, American Bar Association, Los Angeles County Bar Association, Beverly Hills Bar Association, Consumer Attorneys Association of Los Angeles

Where Complexity Arises

When Property Division Becomes More Complex

Some divorces divide cleanly. Others carry hidden complexity that only surfaces once someone looks closely at how an asset was acquired, funded, or grown. In our experience, property division becomes genuinely complex — and the value of experienced counsel rises sharply — when any of the following is true:

  • One spouse owned real estate or a business beforethe marriage
  • A business increased in value while the couple was married
  • Separate and community funds were mixed in the same account or asset
  • Executive or equity compensation— RSUs, options, or carried interest — is involved
  • Family trusts or inherited assets are part of the picture
  • Real estate appreciated significantly during the marriage
  • One spouse managed the finances and the other has limited visibility

If two or more of these describe your situation, the questions below are the ones that will shape your outcome. The rest of this page walks through each — the law, the formulas, and how they play out in real Beverly Hills cases.

The Framework

What Is Community Property Under California Law?

Family Code §760 establishes that, with limited exceptions, all property acquired by either spouse during the marriage is community property.Family Code §770 carves out separate property: what a spouse owned before the marriage, and what a spouse receives during the marriage by gift or inheritance.Family Code §2550 then requires the court to divide the community estate equally, absent a written agreement to the contrary. Where that dividing line falls often depends on the date of separation, which fixes the point after which new earnings are no longer community.

The Fiduciary Duty That Governs Property Management

Family Code §721 requires spouses to deal with each other in the highest good faith while the marriage is intact, including full access to financial records affecting community property. This duty matters directly in property division cases, since a spouse who conceals or mismanages community assets during the marriage can face consequences when the estate is finally divided.

Tracing and Commingled Assets

The line between separate and community property is rarely as clean as the statute suggests. When separate funds are deposited into a joint account, used to pay down a jointly titled mortgage, or invested alongside community funds, tracing becomes necessary to determine what portion of the resulting asset remains separate.

Courts require clear documentation, not general recollection, to support a tracing claim, which is why financial records matter as much as legal argument in these cases.

Worked example· Commingled savings

A spouse enters the marriage with $300,000 in a brokerage account (separate property). During the marriage, both spouses’ paychecks are deposited into the same account, and withdrawals are made for household expenses. Years later, the account holds $500,000. Because separate and community dollars were mixed and spent without records, the separate-property claim is only as strong as the tracing behind it. With statements showing the original $300,000 was never spent, that portion can remain separate. Without them, a court may treat the entire balance as community.

A representative Beverly Hills property division case may involve:

  • A primary residence in the Beverly Hills Flats, Trousdale Estates, or the Golden Triangle, often with significant equity
  • Vacation or investment real estate in California or out of state
  • A closely held business, production company, or professional practice
  • Equity compensation, including restricted stock units, options, and performance shares
  • Retirement accounts and pension benefits requiring a Qualified Domestic Relations Order
  • Royalties, residuals, and other entertainment industry income
  • Family trust interests and inherited assets
  • Art, collectibles, and other high-value personal property

Real Estate

Real Estate Division in Beverly Hills

Real estate is frequently the single largest asset in a Beverly Hills property division, and it raises characterization questions more often than any other asset category.

The Moore/Marsden Analysis for a Separately Owned Home

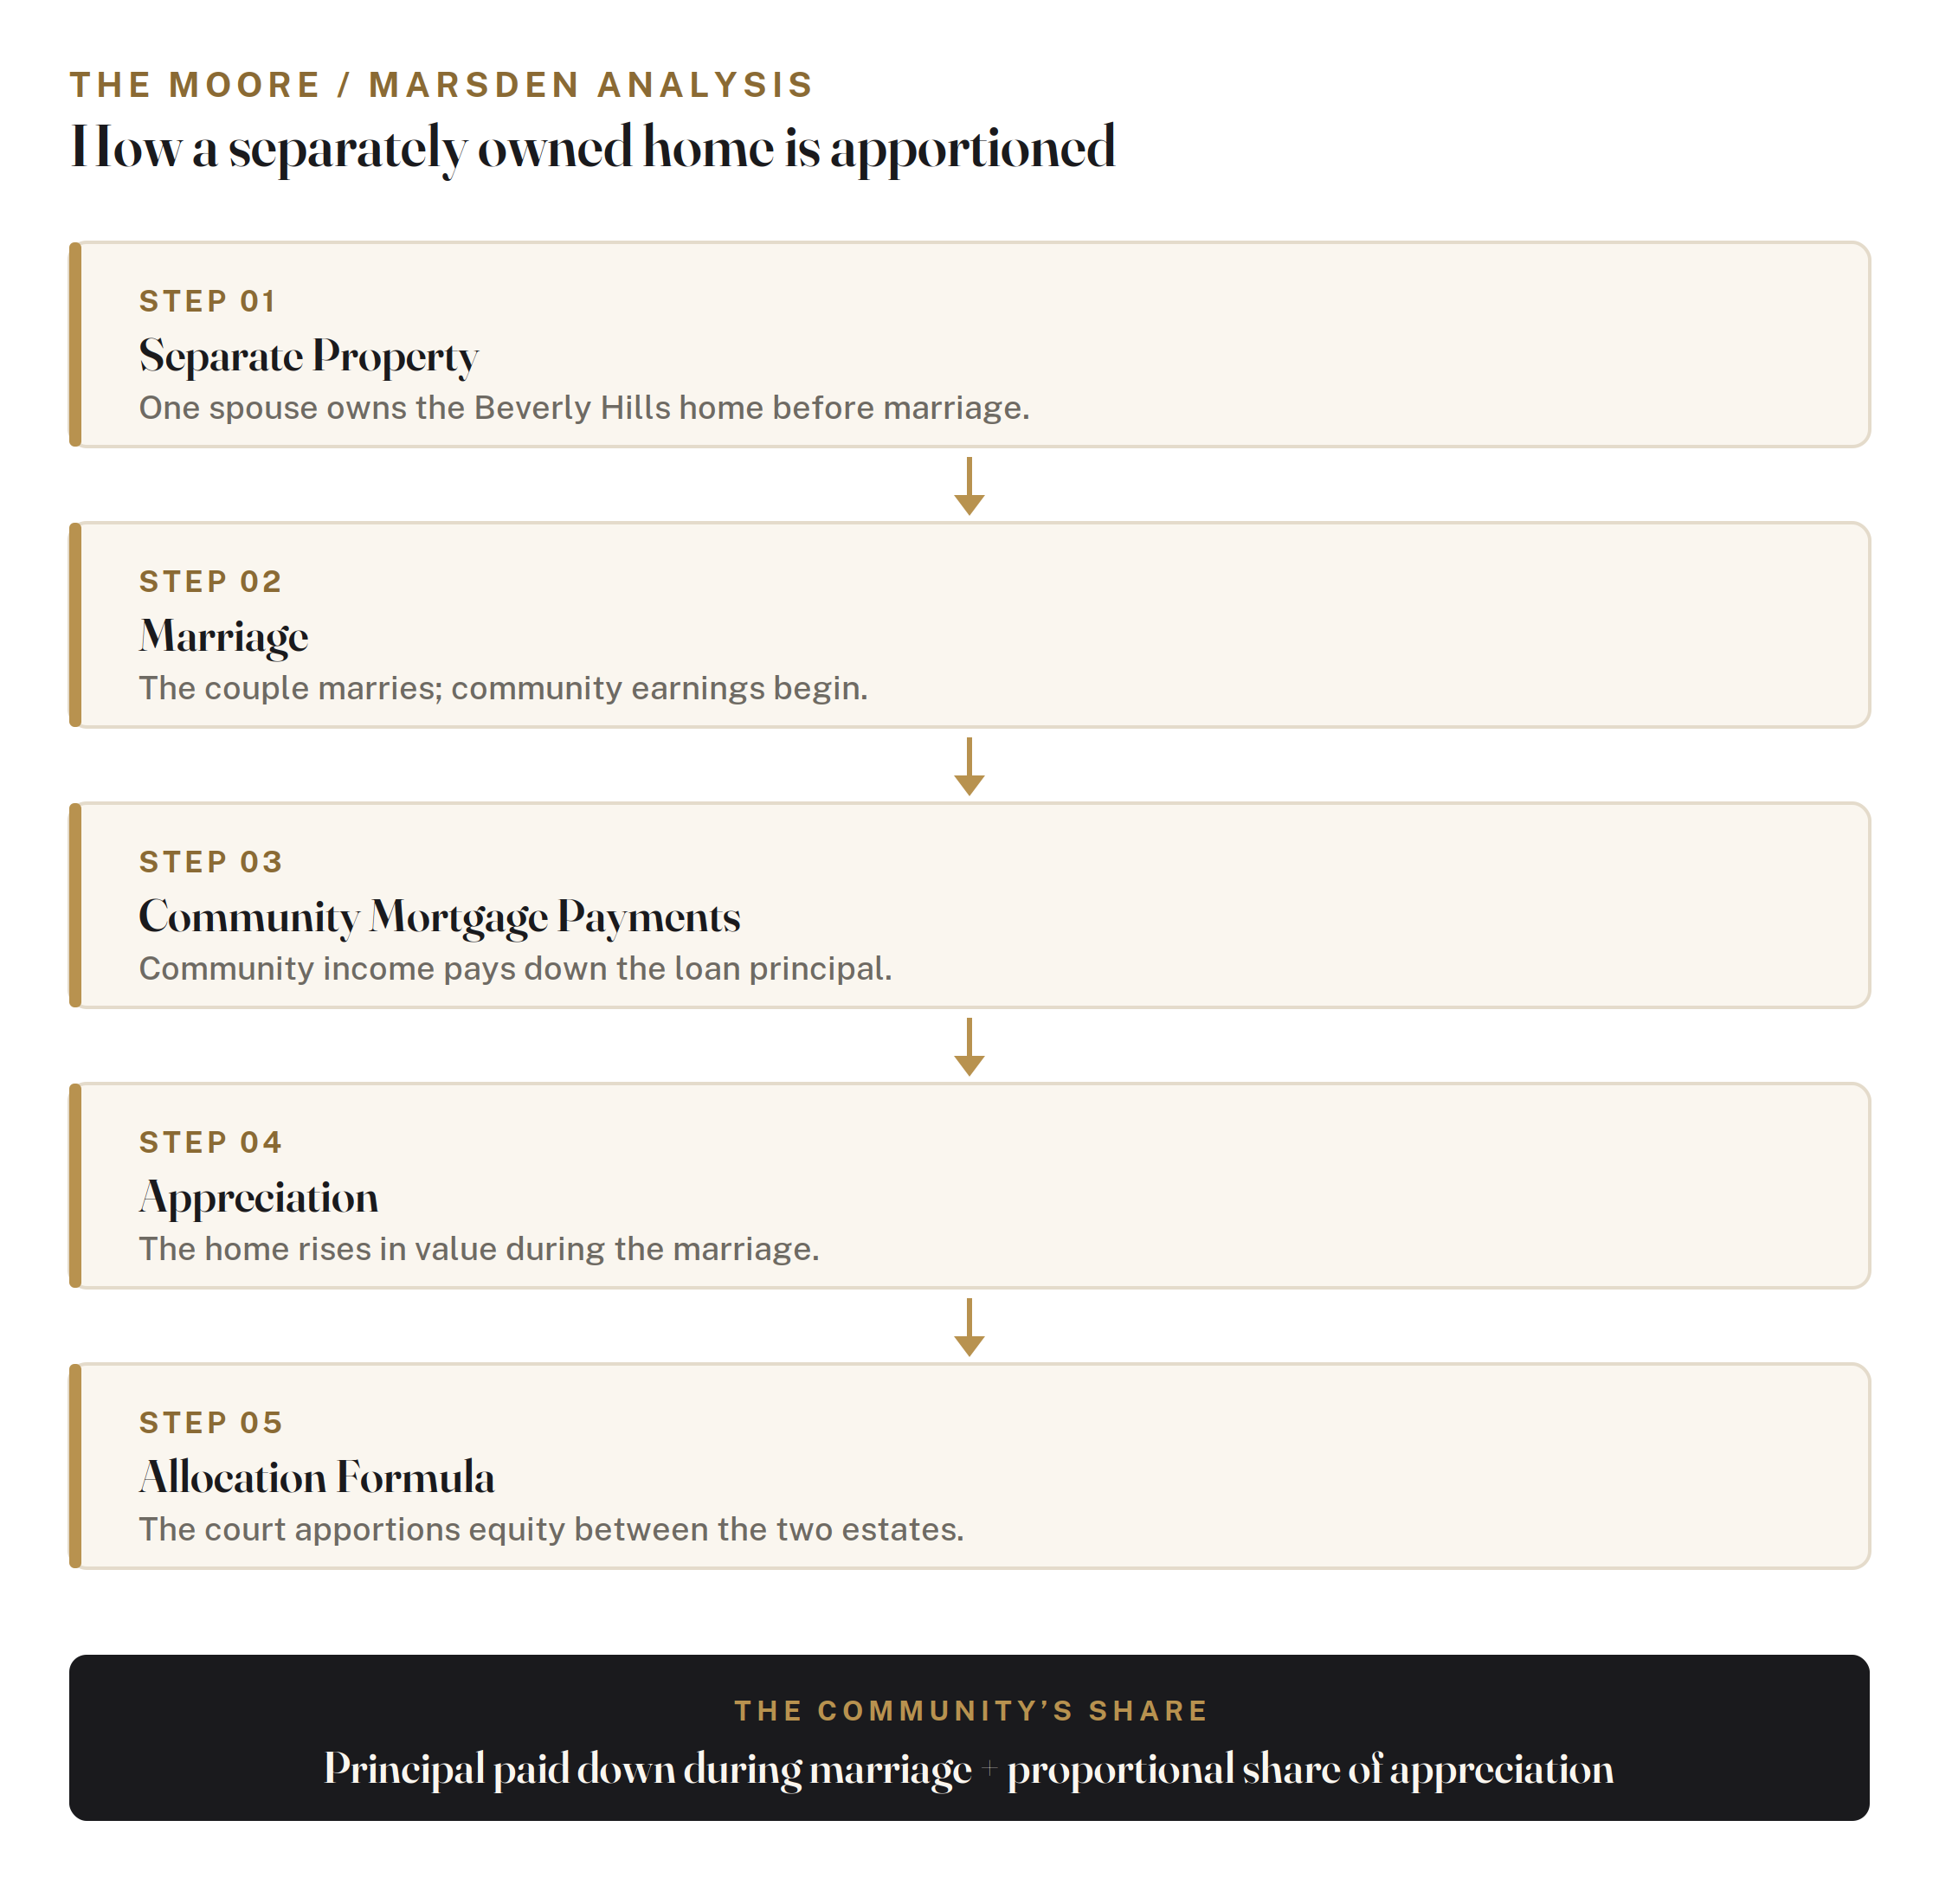
Where one spouse owned a home before the marriage and the couple used community funds — income earned during the marriage — to pay down the mortgage, In re Marriage of Moore and In re Marriage of Marsden together establish a formula for apportioning the resulting equity between the separate-property owner and the community.

The community receives credit for the principal paid down during the marriage, plus a proportional share of the home’s appreciation, while the spouse who owned the home before the marriage retains the premarital equity as separate property.

How community mortgage payments earn the community a share of a separately owned home.

Worked example  · A Beverly Hills home bought before marriage

A spouse buys a Beverly Hills home before marriage for $2 million. During the marriage, community earnings pay down the mortgage, and by the time of divorce the home is worth $5 million.

California does not simply label the $3 million of appreciation as separate or community. Instead, the court applies the Moore/Marsden formula: the community is credited with the principal it paid down during the marriage, plus a proportional share of the appreciation based on the community’s contribution to the purchase price. The premarital equity, and appreciation tied to it, stays separate. The result is a defined percentage interest for each estate rather than an all-or-nothing outcome — and small changes in the tracing can move six or seven figures.

Reimbursement for Separate Property Down Payments

Family Code §2640 entitles a spouse to reimbursement for separate property contributions, such as a down payment, toward the acquisition of community property, absent a written waiver. This reimbursement is dollar-for-dollar, without interest or adjustment for appreciation, and requires the contributing spouse to trace the funds to a separate property source.

Refinancing and Title Changes

Refinancing a home during the marriage, or adding a spouse to title, can change how the property is characterized and can affect or eliminate a §2640 reimbursement claim depending on how the transaction was documented. These transactions deserve careful review well before property division negotiations begin.

Options for Dividing the Family Home

Common outcomes include selling the property and dividing the proceeds, one spouse buying out the other’s interest at an agreed or court-determined value, or a deferred sale tied to a specific future event, such as a child completing high school. The right choice depends on the family’s overall financial picture and each spouse’s ability to carry the property independently.

The Moore/Marsden Analysis

Business Interests

Business Valuation and Division in Beverly Hills

Beverly Hills property division cases frequently involve a business owned by one or both spouses. Where the business was owned before the marriage but grew during it, California courts apply one of two formulas to apportion that growth between separate and community property. The same principles carry over to a closely held business or professional practice.

The Pereira formula. Under Pereira v. Pereira, where the business grew primarily because of a spouse’s personal effort and skill during the marriage, the separate-property owner is credited with a fair rate of return on the business’s value at the time of marriage, and the remaining growth is treated as community property.The Van Camp formula. Under Van Camp v. Van Camp, where the business’s growth is primarily attributable to the nature of the business itself — its capital, market position, or workforce — rather than one spouse’s personal labor, the community is instead credited with the reasonable value of that spouse’s services, and the remaining growth stays separate property.The threshold question is what drove the growth — the owner, or the business itself.

Choosing between these two formulas, or a hybrid of both, depends heavily on the specific facts of how the business grew, and the choice can substantially affect the outcome. Side by side, the two formulas point in opposite directions:

Pereira Van Camp
Growth driven by the owner’s personal labor and skill Growth driven by the business’s own capital and market position
Tends to produce more community property Tends to produce more separate property
Emphasizes the owner’s efforts during marriage Emphasizes the business itself as the engine of growth
Separate estate keeps a fair return on premarital value Community is paid the reasonable value of the owner’s services
Favored when a founder’s hands-on work drove results Favored when passive capital or brand drove results

We work with business appraisers to build the factual record that supports the more favorable formula for our client’s position.

How a Business Is Valued

Before either formula can be applied, the business itself has to be valued — and the method matters as much as the math. Appraisers generally work from one or more of these approaches, and a credible valuation usually cross-checks several:

  • Capitalization of earnings. Converts a normalized single year of earnings into a value using a capitalization rate. Common for stable, established practices and service businesses.
  • Discounted cash flow (DCF). Projects future cash flows and discounts them to present value. Useful where growth is expected to change materially over time.
  • EBITDA multiples. Applies a market multiple to earnings before interest, taxes, depreciation, and amortization — a quick market-anchored gauge that has to be adjusted for owner compensation and one-off items.
  • Market comparables. Looks to actual sale prices of similar businesses. Persuasive when genuinely comparable transactions exist, and weak when they don’t.

The choice among these methods — and the normalizing adjustments behind them, such as adding back an above-market owner’s salary — is exactly where valuations diverge and disputes arise.

Nicole’s business background lets her engage with these assumptions directly rather than deferring to whichever number is put in front of the court.

Buy-Sell Provisions and Operating Agreements

Where a business has co-founders, investors, or an existing operating or shareholder agreement, that governing document often addresses what happens to an owner’s interest upon divorce.

We review these documents early, since they can affect both valuation methodology and a spouse’s practical ability to retain or liquidate their interest.

Retirement

Retirement Accounts and Deferred Compensation

Family Code §2610 requires the court to make such orders as necessary to ensure that each spouse receives their full community property share of any retirement plan. For most employer-sponsored plans, this requires a Qualified Domestic Relations Order — a separate court order directing the plan administrator how to divide the account without triggering early withdrawal penalties. Public pensions, including CalPERS and CalSTRS, use a similar Domestic Relations Order and typically require the plan to be joined as a party to the divorce.

Only the portion of a retirement account attributable to the marriage is community property. Family Code §2552 generally requires the court to value community assets as close as possible to the time of trial, which matters considerably for accounts whose value fluctuates with the market. Deferred compensation and unvested equity awards add a further wrinkle, since a portion earned during marriage may be community even if it vests later.

Industry Assets

Entertainment Industry Assets in Beverly Hills Property Division

Royalties and residuals: Income from creative work produced during the marriage is community property, even when payments continue arriving years after the work was completed. The community’s interest in that future income stream must be valued and either divided directly or offset against other assets.Intellectual property: Beyond the income itself, copyrights, trademarks, and master recording rights developed during the marriage may be divisible community assets in their own right, raising both valuation and creative-control questions that a straightforward dollar division tends to overlook.

Disclosure

Hidden and Undisclosed Assets

California’s mandatory disclosure rules require both spouses to provide complete and accurate information about assets, debts, and income under penalty of perjury. Where one spouse has significantly more visibility into the couple’s finances than the other, undisclosed assets or income sometimes surface only through targeted discovery.

We work with forensic accountants and other outside financial professionals when a lifestyle analysis or a deeper review of business records is warranted to confirm that a proposed division reflects the full marital estate, not just what was voluntarily disclosed.

Debts

Community Debt Division in Beverly Hills

Property division is not just about dividing assets. Community debts — mortgages, credit card balances, and lines of credit incurred during the marriage — are generally divided along with community assets. Where one spouse incurred debt for a separate property purpose, or after the date of separation, tracing the source and purpose of that debt matters just as much as tracing a claimed separate property asset.

The Tax Layer

Tax Consequences of Property Division

Not all dollars in a property division are equal. A dollar in cash, a dollar in appreciated stock with a low cost basis, and a dollar in a pre-tax retirement account carry very different real-world value once taxes are accounted for. A settlement that looks equal on paper — one that trades a spouse’s cash for an equivalent face value of retirement funds, for example — can be significantly unequal after tax consequences are factored in.

The tax questions that most often change the real value of a Beverly Hills division include:

  • Capital gains and cost basis. An asset’s built-in gain travels with it. Taking the appreciated stock or the low-basis rental means inheriting the tax bill that comes due on sale.
  • Depreciation recapture. Investment real estate that has been depreciated can trigger recapture taxed at a higher rate on sale — a cost easy to miss when comparing properties by equity alone.
  • Retirement withdrawals. Pre-tax retirement dollars are taxed as ordinary income when drawn, so a 401(k) balance is worth less than the same number in a Roth or in cash.
  • Stock options and RSUs. The timing of exercise, vesting, and sale drives whether gains are taxed as ordinary income or capital gain — and who bears that tax.
  • Deferred and built-in taxes. A business interest or installment sale can carry embedded future tax that should be discounted from its headline value.

The after-tax character of major assets need to be evaluated before finalizing a proposed division, particularly where a settlement trades one asset category for another, such as real estate equity for a business interest or a retirement account for current cash.  We coordinate with your CPA or tax counsel so the numbers you agree to are the numbers you actually keep.

Step by Step

How Property Division Works in Beverly Hills: The Process

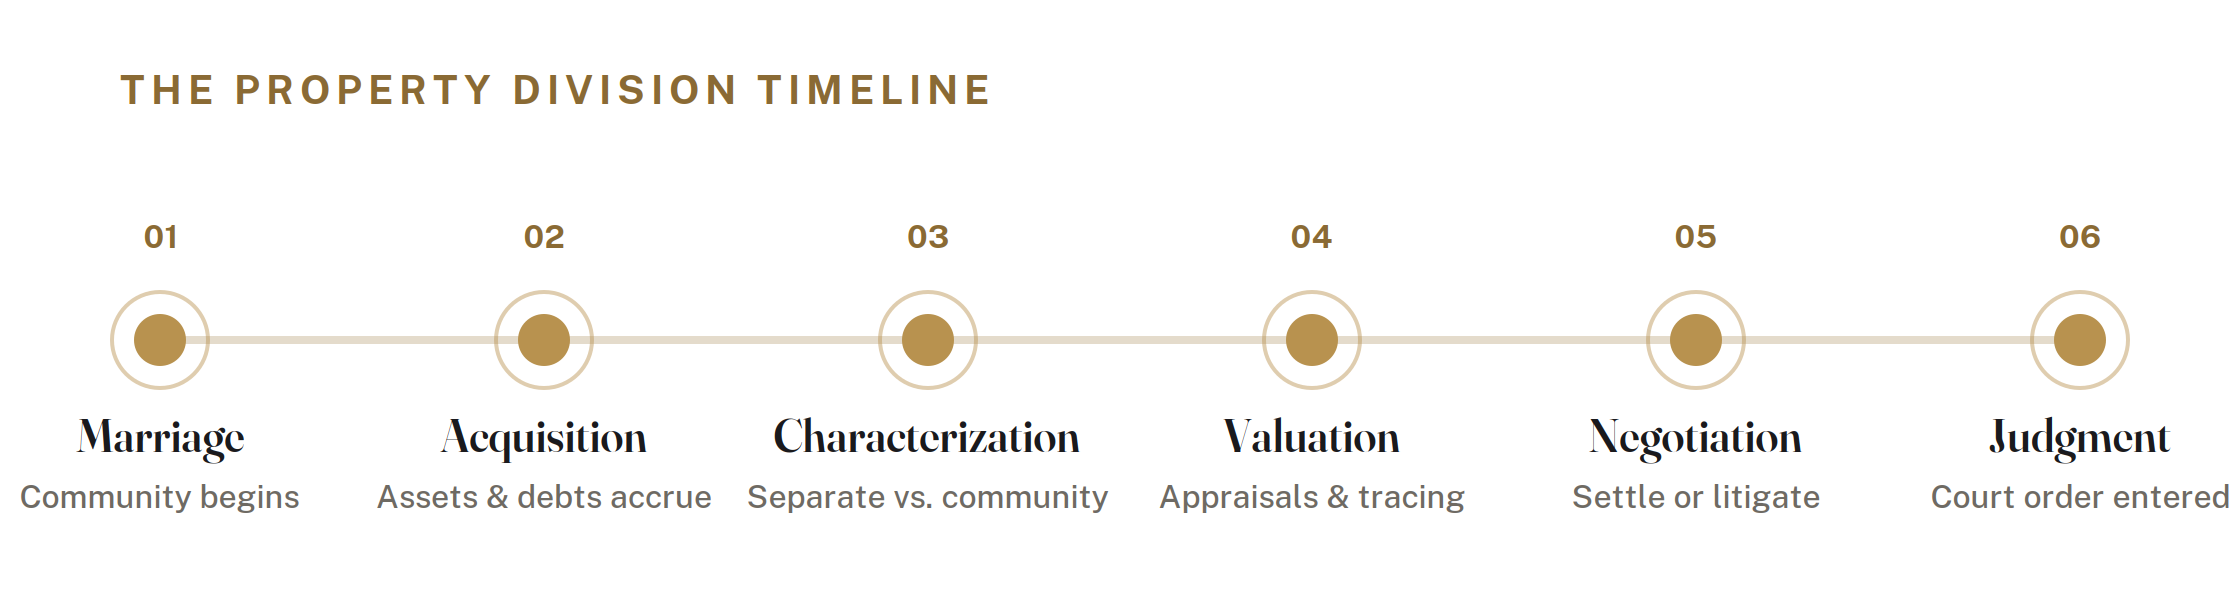
Property division follows a general sequence within the broader divorce case, though the pace and complexity depend heavily on what assets are involved.

The path from marriage to judgment — most of the outcome is decided in the middle three steps.

  1.   Identifying the Marital Estate. We work with you to identify every asset and debt, including ones that may not be obvious, such as deferred compensation or a business’s goodwill.
  2.   Characterization. Each asset is classified as separate, community, or a mix of both, based on when and how it was acquired and on any available tracing evidence.
  3.   Valuation. Real estate, businesses, and other significant assets are valued, often with the help of appraisers or forensic accountants, as close to the time of trial as the case allows.
  4.   Applying the Right Legal Framework. Moore/Marsden, Pereira, Van Camp, and §2640 reimbursement claims are applied where relevant to determine each spouse’s actual interest.
  5.   Negotiation or Litigation. Armed with an accurate valuation and characterization, we negotiate a settlement or, where necessary, litigate the disputed issues before the court.
  6.   Drafting the Division. The final agreement or judgment specifies exactly how each asset is divided, including any Qualified Domestic Relations Orders needed for retirement accounts.
  7.   Implementation. We follow through on the practical steps required to actually transfer titles, retitle accounts, and finalize retirement plan divisions after judgment.

Pitfalls

Common Property Division Mistakes

Even cooperative divorces can produce an unfair or unenforceable division when the process skips important steps. The most costly — and most avoidable — mistakes we see are:

  • Waiting too long to collect financial records. Statements, tax returns, and closing documents are easiest to gather while the marriage is intact; tracing gets harder as accounts turn over.
  • Assuming title controls ownership. Whose name is on the deed or account often does not decide characterization — how and when the asset was funded usually matters more.
  • Ignoring tax consequences. Accepting an asset by face value, without modeling cost basis and deferred tax, can quietly hand the other spouse the better half of an “equal” split.
  • Accepting informal business values. A number both spouses “agree feels right” is not a valuation, and it rarely survives scrutiny if the deal later unravels.
  • Forgetting reimbursement claims. The §2640 right to recover a separate-property down payment is routinely overlooked because both spouses assume the home is simply community.
  • Overlooking deferred compensation. Unvested RSUs, options, pensions, and residuals earned during the marriage are community property even if they pay out later.
  • Treating a refinance or title change as immaterial. These transactions can already have altered characterization or waived a reimbursement right before negotiations even begin.

Quick Answers

Common Questions About Beverly Hills Property Division

Direct answers to the questions clients ask first. For the fuller, case-specific version, see the FAQ at the end of this page.

Is my house community property if I bought it before marriage?

The home starts as your separate property, but it usually does not stay entirely separate. If community income paid down the mortgage during the marriage, the Moore/Marsden formula gives the community a share of both the principal paid and a proportional part of the appreciation. You keep your premarital equity as separate property; the community earns an interest in the growth its payments helped create. Tracing your original contribution is what protects your separate share.

Can my spouse claim part of my business?

Often, yes — at least part of it. A business you started during the marriage is generally community property. One you owned beforehand stays separate at its premarital value, but growth during the marriage is apportioned under Pereira or Van Camp, depending on whether that growth came from your personal effort or from the business’s own capital and market. Your spouse may be entitled to a community share of the increase, typically established through a business appraisal.

How are RSUs and stock options divided?

Equity awards are divided based on what portion was earned during the marriage. California courts use time-based formulas — commonly the Hug or Nelson approach — that compare the grant, vesting, and separation dates to decide how much of each tranche is community versus separate. Unvested awards still count if the work that earned them occurred during the marriage. Because vesting and tax timing interact, these are easy to undervalue without careful, award-by-award analysis.

What happens if my spouse hides assets?

Concealing assets breaches the fiduciary duty spouses owe each other under Family Code §721 and violates California’s disclosure rules, which are made under penalty of perjury. When hidden assets are suspected, targeted discovery and a forensic accounting review — including lifestyle analysis and tracing through business records — can surface them. The consequences are real: a court can award the concealed asset, or its value, disproportionately or entirely to the other spouse, along with sanctions and fees.

Does refinancing change who owns the home?

It can change more than people expect. Refinancing during the marriage, or adding a spouse to title, may alter how the property is characterized and can reduce or eliminate a §2640 reimbursement claim for a separate-property down payment, depending on how the paperwork was drafted. Courts look at the documents and the parties’ intent, not just the loan. Any refinance or title change deserves review before you rely on assumptions about ownership.

Our Approach

How Duncan Family Law Approaches Property Division

Every property division matter we handle is built around one goal: ensuring the division accurately reflects the full marital estate.

Coordinated Use of Outside Professionals

We work with experienced business appraisers, real estate professionals, and forensic accountants when a case calls for expert analysis, and we ensure their conclusions are usable in negotiation or at trial.

Trial-Ready Preparation

Most property division disputes settle, but only once both sides understand what a court would actually do. We prepare every case as if it will be tried, which strengthens our negotiating position and protects clients if a fair settlement cannot be reached.

Confidentiality for Beverly Hills Clients

Property division cases involving a business, a public profile, or significant family wealth carry real privacy concerns. We work to limit public exposure of sensitive financial details wherever California procedure allows.

Choosing a Path

Property Division Compared to Mediation and Collaborative Divorce

Property division issues do not have to be resolved through contested litigation. Many Beverly Hills clients address these same questions through divorce mediation or a collaborative divorce process, with Duncan Family Law serving as consulting or collaborative counsel rather than litigation counsel.

The legal characterization and valuation principles described on this page apply regardless of which process is used to resolve them. What changes is how privately, and how cooperatively, the couple reaches that resolution. The same is true for spousal support, child support, and custody — related issues that are frequently negotiated alongside the property division.

Local Realities

Property Division in Beverly Hills: What Sets These Cases Apart

Beverly Hills is a small city in terms of area and population, but the concentration of real estate value, business ownership, and entertainment-industry wealth here means that even a modest marriage can involve a property division case of considerable complexity. Homes in the Flats, Trousdale Estates, and the Golden Triangle — and in neighboring luxury markets such as Holmby Hills and Bel Air — regularly carry equity that turns a single characterization question into a seven-figure dispute.

Median single-family home values in the 90210 ZIP code routinely exceed four million dollars, which means a Moore/Marsden or §2640 analysis on the family home alone can carry six or seven figures of consequence. Closely held businesses, family trusts, and entertainment royalty streams are common enough in Beverly Hills households that a property division case here often requires the same financial rigor as a much larger commercial dispute. These matters are filed in the Los Angeles County Superior Court and heard in its family law divisions, including the Stanley Mosk Courthouse.

Duncan Family Law approaches every Beverly Hills property division case with those local realities as the starting point, not an afterthought.

The Difference

Why Beverly Hills Couples Choose Duncan Family Law for Property Division.
  • Exclusive family law focus: Duncan Family Law handles only divorce and family law, so its knowledge of California’s community property, characterization, and valuation rules stays current and practically applied.
  • Trial-ready preparation: Every case is prepared as if it will be tried, which gives clients real leverage in negotiation and a credible path forward if settlement is not possible.
  • Coordination across professionals: We work directly with appraisers, forensic accountants, and real estate professionals so every valuation holds up under scrutiny.
  • Confidential, discreet representation: We understand why privacy matters to Beverly Hills clients and structure our approach with that discretion in mind.

Begin

Speak With a Beverly Hills Property Division Attorney

The most valuable property division decisions are often made long before trial. Whether your case involves a family business, executive compensation, significant real estate, or substantial investment assets, obtaining informed legal advice early can materially change the ultimate outcome — because by the time settlement talks begin, the tracing, characterization, and valuation that drive the result are already largely set.

The Firm

About Attorney Nicole Duncan

Duncan Family Law is led by Nicole Duncan, a California family law attorney who founded the firm to provide focused, strategic representation in divorce and family law matters. Nicole represents Beverly Hills clients from the firm’s Beverly Hills office on Camden Drive and its Los Angeles office on West 3rd Street. Learn more about the firm.

Credentials

  • California State Bar Number: 328341 (Active)
  • Colorado State Bar Number: 54630 (Active)
  • Juris Doctor (J.D.): Whittier Law School
  • B.A.: University of Southern California, Marshall School of Business (Lloyd Greif Center for Entrepreneurial Studies)
  • Certificate in International Law: King’s College London
  • Admitted to practice: 2019

Professional Associations

Nicole regularly appears before the Los Angeles County Superior Court, including at the Stanley Mosk Courthouse and in the surrounding family law divisions. Her background in business is especially useful in property division matters involving business interests, equity compensation, and real estate.

Sources of Authority

Statutes · California Family Code

  • 760 (community property) · §770 (separate property) · §721 (spousal fiduciary duty) · §852 (transmutation) · §2550 (equal division) · §2552 (valuation date) · §2610 (retirement orders) · §2640 (separate-property reimbursement).

Leading cases

In re Marriage of Moore · In re Marriage of Marsden · Pereira v. Pereira · Van Camp v. Van Camp.

Google Review

“From the initial consultation through the final hearing, Duncan Family Law was outstanding. Nicole is organized, knowledgeable, and fearless in court. I recommend her without hesitation.”

Moncef A.

Google Review

“Nicole Duncan is an outstanding family law attorney. She helped me navigate a complicated divorce and custody dispute in Los Angeles and achieved a result that exceeded my expectations. Opposing counsel clearly respected her preparation and legal knowledge. Duncan Family Law is absolutely among the top divorce law firms in Los Angeles.”

Justin Y.

Google Review

“If you need a strong divorce attorney in Los Angeles, call Duncan Family Law. Nicole is responsive, strategic, and truly fights for her clients. I am so grateful I found this firm.”

Daniele D.

Google Review

“Duncan Family Law provided exceptional representation during one of the hardest periods of my life. Nicole Duncan is knowledgeable, aggressive when needed, and incredibly professional.”

Ricky B.

Google Review

“Nicole was an outstanding divorce lawyer who helped me navigate child custody with clarity and care. I’m incredibly grateful for her support.”

Moulouk A.

Google Review

“I honestly couldn’t have asked for a better lawyer. She’s incredibly honest, always responsive, and truly cares about her clients. Nicole did whatever it took to get things done and even went above and beyond.”

JA

Google Review

“I cannot recommend Nicole Duncan highly enough. She listens to me, believes me, and fights for me and my child as if we were her own family, with professionalism, compassion, and an incredible command of the law.”

Alexis S.

Google Review

“Divorce proceedings are painful at best, but Nicole Duncan was a shining light through it all. I really appreciated her calm demeanor throughout the process. Her guidance ended in a final decision that left me very pleased.”

Sebastian R.
Frequently Asked Questions About Property Division in Beverly Hills
What is community property in a Beverly Hills divorce?

Under Family Code §760, property acquired by either spouse during the marriage is generally community property and subject to equal division under §2550. Property owned before the marriage, or received during the marriage by gift or inheritance, is separate property under §770.

How is our house divided if one of us owned it before the marriage?

If community funds were used to pay down the mortgage during the marriage, the Moore/Marsden formula applies, giving the community credit for the principal paid down plus a share of the appreciation, while the original owner keeps the premarital equity as separate property.

Can I get reimbursed for a down payment I made from my own savings?

Generally yes. Family Code §2640 entitles you to dollar-for-dollar reimbursement for separate property contributions toward community property, such as a down payment, provided you can trace the funds and have not waived that right in writing.

How is a business divided in a Beverly Hills divorce?

If the business was owned before the marriage and grew during it, courts apply either the Pereira or Van Camp formula depending on whether that growth resulted from personal effort or from the nature of the business itself. A business appraiser is typically needed to establish the underlying values.

How are retirement accounts divided in California?

Family Code §2610 requires the court to ensure each spouse receives their full community property share of a retirement account, typically through a Qualified Domestic Relations Order for private plans or a Domestic Relations Order for public pensions like CalPERS or CalSTRS.

Are entertainment royalties divided in a Beverly Hills divorce?

Yes. Royalties and residuals earned from work created during the marriage are community property, even if the payments continue arriving after separation. The value of that future income stream must be assessed and divided or offset.

What happens if my spouse hides assets during property division?

Concealing assets breaches the fiduciary duty spouses owe each other under Family Code §721 and violates California’s mandatory disclosure rules. Where hidden assets are suspected, targeted discovery and forensic accounting review can often uncover them.

Does refinancing our home change how it will be divided?

It can. Refinancing or adding a spouse to title during the marriage may affect or eliminate a §2640 reimbursement claim depending on how the transaction was documented, which is why these transactions deserve careful review before property division negotiations begin.

Do I have to sell the house in a Beverly Hills divorce?

Not necessarily. Common alternatives include one spouse buying out the other’s interest or a deferred sale tied to a future event, such as a child finishing school. The right option depends on both spouses’ overall financial circumstances.

When is a business or property valued in a divorce?

Family Code §2552 generally requires the court to value community property as close as possible to the time of trial, rather than the date of separation, which can matter significantly for assets whose value fluctuates.

Can property division be resolved outside of court?

Yes. Many Beverly Hills couples resolve property division through mediation or a collaborative divorce process rather than contested litigation. The same characterization and valuation principles apply regardless of the process used to reach agreement.

How long does property division take in a Beverly Hills divorce?

Straightforward cases can resolve within the standard six-month waiting period. Cases involving business valuations, real estate tracing, or contested retirement accounts typically take longer, since accurate valuation is essential to a fair division.

Are debts divided the same way assets are in a Beverly Hills divorce?

Generally yes. Community debts incurred during the marriage are divided along with community assets, while debt tied to a separate property purpose or incurred after separation typically remains that spouse’s individual responsibility, subject to tracing the same way an asset would be.

Does it matter whether I receive cash or stock in my property division?

Yes. Cash, appreciated stock, and pre-tax retirement funds carry different after-tax value even at equal face amounts. We evaluate the tax character of a proposed division before treating it as truly equal.

What if my spouse and I disagree on the value of our business?

This is common, and it is usually resolved through a business appraiser — sometimes a single neutral expert both sides agree to, and sometimes competing experts whose reports are compared. The choice of the Pereira or Van Camp formula can matter as much as the appraised value itself.

Begin

Choosing the right attorney may be the most important decision you make in your divorce.